Author: benefitadmin

  • Cargo Cult Map

    Just because it looks like one doesn’t mean it is one

    Are your networks fit for purpose or are you drawing them out of superstition?

    Child's puzzle, whose kite is whose?

    Variety is (not always) the Spice of Life

    Cargo cults were first seen in the Pacific after WWII. Islanders watched US forces build airstrips. Then planes arrived full of cargo. The war ended, the airstrips closed and the planes stopped coming. Logic suggested that if you build airstrips, the planes will come. And so the islanders copied as best they could in the vain hope that they could attract new planes with more cargo.

    A quick search on “cargo cult management” will bring up a raft of articles on how the same logic gets applied in business circles. We make assumptions and copy without a proper understanding of the original situation. And then, like the poor old Pacific islanders, we wonder why the planes won’t come.

    A few years back I worked on a programme that introduced BM into parts of the NHS. Within a couple of months we saw that people were drawing their Benefits Dependency Networks in a variety of ways. Some of this was due to the tools they had. Visio obviously offered more depth than filling cells in a spreadsheet and the diagrams would look very different in style, if not in content. But it wasn’t just the tools. People adapted the BDN to their own understanding of the method and their personal preferences. At the time I viewed it as the evolution of local dialects, a natural progression and not a major issue. Indeed, possibly a good thing.

    Now, I’m not so sure. Maybe natural selection isn’t yet happening as it should and the weak are thriving. I’ve started to come across a few BDNs that can’t perform their function. Ones where the links are all right angled connections that overlap so it appears that everything in one column connects to everything in the next. Others have objectives in the middle so the chain of cause and effect isn’t rational and the cart is pulling the horses. There are people out there who are mistaken about the quality of their method and the subsequent benefits they choose to deliver. They are not doing quite as well as they think they are.

    The APM specific interest group wrote a pamphlet on embedding BM in the enterprise. I think it’s time we all worked on embedding good BM in the enterprise. I don’t want to go as far as mandating one methodology. I’ve got my own (superior, naturally…) way of doing things and I don’t want to give it up. Many other people will feel the same way. However, I think there’s scope to use our formal and informal networks to share good practice on the fundamentals. When people work in a vacuum their practices change over time without anyone checking if they are still valid. Before long the minor dialect change risks turning into nonsense that’s performed more out of superstition than business value.

  • The Decision Guide

    Decision Guide

    A Guide gets you through difficult territory. They won’t pick your destination, though they may make suggestions. “This summit has a better view.” “We can get to that destination in half the time.” You are in charge of where you want to end up.


    The Guide won’t carry your bags. Your party does the heavy work. What they will do is lead you by the best route to where you want to be. Their knowledge of the area and experience of previous journeys means they can avoid the pitfalls and dead-ends and select easier and quicker paths.

    In business terms, that’s what a Decision Guide does. It’s still your business, you understand what you are about, you make the decisions on what you want to change and your people do the work to change it. I bring the subject matter expertise in making business choices and the experience of seeing how it’s been done before.

    My role is to lead you through the process of making those decisions so that you choose the best option and take the optimal route to business success. I use Benefits Management to help you choose the right thing, for the right reasons and see it delivered.

  • Down the Market

    Imagine your programme is pickling a shark. Do you know what the shark is worth?

    This is one of those analogy things so please suspend your disbelief and work with me. It should all make sense in the end. I’m going to apply some ideas from the World of Art to the world of intangible benefits, the ones that don’t result in an easily counted bag of cash.


    As a Benefits Manager, part of my job is to work out if / why Plan A is the best use of our scarce resources, what makes it better than Plan B and all the other plans we could spend on. This isn’t helped when there is no common understanding of Plan A’s added value, how much its benefits will outweigh its costs.

    Part of the reason we struggle to value any intangible product / service is because we don’t think about the market where it’s bought and sold. Our programme is going to create something of value, a solution that realises benefits worth more than its costs. Think of it as our Masterpiece. It’s a work of art, not a commodity. Its value will be set by a select few stakeholders in the art market, not by hundreds of traders in the stock market.

    It’s bespoke, complicated and unique. Other programmes’ outcomes may be similar, but they are not exactly the same. It’s not so much one barrel of oil out of millions, it’s more like Damien Hurst’s big dead shark in a tank of formaldehyde. It is considered an exemplar of artistic skill (by the people who like that sort of thing). It’s made from relatively cheap materials, so there’s no scrap value worth talking about. If it succeeds, then it’s a priceless art. If not, it’s worthless junk. It’s original and outside any established school or style so there’s no benchmark against which to compare it.

    Like the dead shark, it could be worth £millions, but it will depend on who you ask and how you ask them. Pricing your programme’s intangible benefits is like selling a work of art, so let’s look at our stakeholders in some different art markets. Our market for the Masterpiece consists of four stakeholder groups:

    • The one client who wants to buy the Masterpiece and has the funds to pay for it
    • One or more suppliers who want to build the Masterpiece
    • Consumers who will use the Masterpiece or the system that delivers it (e.g. our staff and their customers)
    • Influencers who have opinions about the Masterpiece and the alternative ways to spend the money

    The value of the Masterpiece will be determined by these four groups. It’s going to sit at the balance point between each group’s understanding of value and their influence / power over the others. The market is where they come together to set the price. So, from an art world point of view what sort of markets could apply here?

    The Private Commission

    This deal is done in private. The client wants something personal and has money burning a hole in their pocket. They find a supplier (artist) they like, and a deal is done between them. No-one else is involved. There are no consumers to work the system between client and supplier and no influencers to affect the price. There is only one benefit, the client’s happiness. The client says that their satisfaction is worth the price they paid.

    The Art Gallery

    This time, the client may not have a single supplier in mind and goes shopping for an artwork. The consumer is the gallery owner who introduces artists to buyers, brokers the deal between them and takes a commission from the sale. The supplier is our artist with an established reputation for high-class modern art. Influencers are a small community of gallery owners, art critics and competing art buyers with money to burn.

    If it’s not a private sale, say the client is buying something to put in a public gallery, then influence expands to people with an opinion on how the client is spending their public money. Or at least, to those people whose opinion the client cares about. The client acts in anticipation of what these stakeholders will think and do.

    The client still decides the value, but that decision is heavily influenced by their understanding of the competition. “I want it because I want it. If I don’t pay £££s, then I will lose it to someone else. I’m comfortable paying £££s. And if it’s not my money, I think I can justify my decision to the press, public, auditors, etc.”

    The Online Auction

    This time, the sale has been advertised world-wide so many more influencers know the art is for sale. Everyone can see the value change in real time as the bids come in. The client still decides the value, but this time they’re better informed. “I paid the market rate for it (which was a lot) but I’m comfortable paying that price.” Or “Bidding stopped much quicker than I expected. I got a bargain…or maybe everyone else knows something I don’t.”

    The Street Market

    Our supplier, the artist decides to ditch the bourgeois art world and take his work to the people, so he hires a market stall for the day and sets up his masterpiece.

    On a busy Saturday there are lots of people passing by who will see his work, but no motivated clients with huge budgets looking for art, maybe the occasional tourist with a bit of spending money. There are certainly lots of influencers around who are happy to voice their lay person’s opinion on the merits of modern art and this piece in particular. Assuming it actually sells, the price will be nowhere near what the gallery could have got.

    Even though we’re talking about the same work of art, the different markets involving different stakeholders come up with vastly different values. The same applies to the intangible benefits of any project / programme. The stakeholders, their beliefs, needs, expectations, resources and power all affect the value they put on the results.

    The Programme as Art

    Very few Benefits Managers get brought in at a programme’s inception to advise on the wisdom of the investment. Usually, the core decision has been made long before the costs and benefits get analysed. The programme sponsor / Senior Responsible Officer, the client in my story wants something big and striking, they’ve cleared the space for it and they’re ready to spend. They’re toying with buying the business equivalent of a pickled shark and want to know if it’s worth the asking price.

    What market forces will affect their decision? Think about the context of the programme and the stakeholders involved, its governance and evaluation arrangements. Who are the four stakeholder groups and how do they interact to determine the programme’s value?

    It could be a privately commissioned piece where the sponsor has a requirement to meet and the cash to spend. They make a deal with the supplier and don’t involve anyone else. They decide if it’s all worthwhile. This is only going to happen for the small stuff within spending limits. Unless you own the company, there will be rules to stop you making big private deals.

    A gallery sale involves the supplier’s sales team in bringing sponsor and supplier together, “What you need is a big dead shark. And we know just where we can get you one.” Once again, the sponsor sets the value. This time though, including the sales team will add a bit to the cost and trim the value.

    Most likely, it will be an auction sale, a job put out to tender within procurement rules. More stakeholders are involved, but they’re all professionals and specialists. They may set boundaries, “You cannot spend more than this. That supplier is not acceptable…” Governance and evaluation influence the choices made and so affect the value. It’s no longer the sponsor’s sole opinion.

    The street market may be a supplier with a solution in search of a problem, “I’ve invented this wonderful app, who wants to buy it? Anyone?…” More likely, it’s supplier and client working together to spread the cost, risk or blame for a choice they’ve already made. “See, it’s not just us. We showed it to everyone and lots of other people thought it was good and wanted a bit of it.”

    At the end of the day, the purpose of Benefits Management is to lend an air of rationality to the exercise of power, and all benefits are a result that a stakeholder perceives to be worthwhile. When it comes to the intangible stuff, there are no simple right or wrong answers, and stakeholder perception is everything. We bring in the rationality by considering the key stakeholders, how they interact and the context in which they operate together, i.e. their market. And hopefully, we get them to agree on a reasonable value for their benefits.

  • Educate, Agitate, Organise

    Motivating change

    [This first appeared as a Guest Blog for Sayers Solutions, May 2013]

    I was going through the family heirlooms and found my dad’s old Trade Union badge blazoned with the motto, “Educate, Agitate, Organise”. It’s a phrase that I haven’t thought about for a long time. It’s good though, when you look at it. If you want to get something changed, this is how to do it, summed in three words.

    Educate – “Did you know that…?”

    Agitate – “Don’t you think we should…?

    Organise – “Then let’s go do…”


    There you have it, how to lead change in three words (and an awful lot of work in the background, glib phrases on their own aren’t enough).

    Educate

    Do you have a message you want to get across? Is it something short, meaningful and bound to make an impact on the people you tell? If it isn’t, can you re-phrase it so it is? Consider the things you don’t know. Your customers and colleagues have their own messages they want to tell you if you give them the right opportunity.

    You can’t change everything at once so look to the benefits. See which change has the biggest impact and who gets the most out of it. Check that it’s feasible and the benefits easily outweigh the costs. That means measuring them and knowing your present baseline. Like I said, an awful lot of work in the background, but it’s best to put the effort in at the start and do something worthwhile. 

    Agitate

    Having chosen to make a change, you’ve got to motivate people to go along with you. You need a compelling story that appeals to your audience. Where you have more than one audience you may need more than one story. But you have to maintain your integrity here. You can’t go about telling everyone what you think they want to hear. Apart from the fact that it’s just wrong, they will catch you out eventually. 

    Organise

    Now comes the dull, hard part. You’ve chosen your Big Idea, everyone’s raring to go, now you’ve got to sort out the practical stuff of who does what, when. There are libraries of books on planning so I’ll not try to cover it here. I will say though that you need to invest more in the change than you do in the hardware. Projects often fail because they spend a lot on the new kit and then try to do business change on the cheap, squeezing it into people’s day-jobs instead of investing in it properly.

    One final thing, don’t treat these three as a sequence of events. Look on them more as a loop. As you learn lessons, re-educate. Agitate constantly, keep up constant communication. Organise flexibly as circumstances change around you.

    So far I’ve failed to find out who invented the phrase. It’s got roots in Victorian socialism, but I haven’t traced its author. Could someone please tell me? I think they deserve a bit of acknowledgement.

  • Embed New Ideas

    From Flavour of the Month to Spécialité de la Maison

    You’ve discovered the ultimate solution, the answer to all your business problems, the business method you’ve waited your entire professional life to find. How will you get your colleagues to take it up? How will you make sure that it will be going strong next year? How will you take it from ‘Flavour of the Month’ to ‘Spécialité de la Maison’?


    Selling the concept

    Everybody says that senior level sponsorship is essential, which it is. So first of all, you’ve got to sell the concepts to the people who matter, the ones who hold the purse strings and who permit you to proceed. Your Method is full of rational and logical value. You are convinced it’s good, so it’s hard to see why no-one else is. Sadly, they haven’t given it the thought and study you have and they don’t always see things your way. You will have to pitch your proposal to them. Even the most un-commercial, egalitarian organisation will have some element of internal competition. You will find yourself competing for senior level sponsorship with all the other initiatives that are vying for their attention, time and budget. No matter what rational value you can bring, you will lose to the person with a more attractive offer. There isn’t space here to take you through all the relevant sales techniques so get the help of your sales and marketing colleagues to make an offer no sponsor can refuse.

    Credibility is a common problem

    People will not take the help you offer if they have no confidence in it. Any successful ‘Head Office imposed business method’ requires credibility to survive and this isn’t easy. Maintaining the Board’s interest and approval is an on-going job. Boards are naturally fickle and it can be safely assumed that any sponsorship at Board level will be fleeting. They are soon distracted by the next big thing or the recurring problems of daily organisational existence.

    If your senior sponsor tells you their work is now done and the Method has been absorbed into the corporate bloodstream, then it’s as good as dead. Line managers will lose interest and it becomes the responsibility of the ‘Resident Expert’. This person is more likely to be appointed for their availability, not their skills. They will be seen as being out of the daily grind, very much a ‘them’ not an ‘us’, the woman / man with a clipboard from head office. Relationships spiral downwards, with poor results and a general desire to back out of the whole process.

    So, you have two audiences to engage, the Board and the end-users.

    Board-level commitment

    The people who tell you that senior sponsorship is essential will also tell you that the way to their hearts is through their pockets. All you have to do is get the promotion of the Method into their personal objectives and they’ll drive it for you. In practice, this will be short-term and output-focussed and won’t get you very far. Your Method may be a work of genius that will change the enterprise significantly but it’s going to be a low priority in any executive’s KPIs. Given personal objectives of, ‘Raise sales in Asia by 10%’ or ‘Ensure all staff complete Form 37a’, which one is going to have the higher reward and so motivate the executive?

    The way to maintain Board-level commitment to something new is to embed its tools and techniques into the standard operating procedures that the execs and seniors use. For example, if you are promoting Benefits Management then make sure that the standard business case template contains a basic Goal Model Map or Benefits Dependency Network. Include a stakeholder analysis in every options appraisal. Have a Benefits trained facilitator aid their strategic planning discussions.

    Using the tools at Board level will encourage, if not mandate their use elsewhere. If a Director has to report to her colleagues using these tools then she will expect her staff to support her by using the same tools.

    Practical application

    So, the Board are on board, how do you bring the rest of the organisation along with them? The end users of the Method are the people who have to make the changes to their working practice and live with the consequences. They are going to be busy and under pressure to deliver. They may be too busy fire-fighting to recognise an extinguisher when it’s offered to them. You cannot expect their instant and enthusiastic cooperation. You will have to convince them of your great idea first, which brings us back to credibility. Dealing with the credibility issue means the Method has to attract the right people to champion the cause and spread the message to their colleagues. In branding terms it is affinity marketing, building on the strengths of both sides.

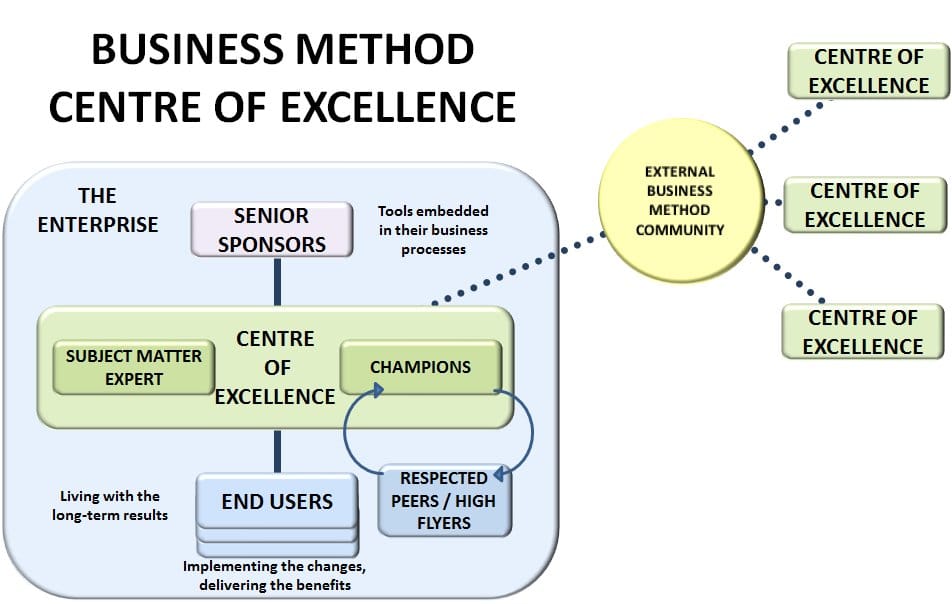
    The actual people who become Champions will obviously depend on the organisation in question. In general terms, we are looking for positive role-models. Often this means respected peers rather than senior staff or head office functionaries, people with a good reputation who lead opinion amongst their colleagues. Respected peers usually have very busy day-jobs which they will not or cannot leave for a permanent role specialising in the Method. They may be available for short-term secondment though.

    If the organisation has a fast-track promotion route or leader development scheme then include a secondment as one of its stages. This gets the bright go-getters involved and they take the skills with them as they rise to the top.

    The downside of this secondment process is that the churn of people passing through risks corrupting the Method. Anyone on a short secondment will still be learning as they leave for their next assignment. There won’t be much improvement over time because all the lessons learned will be from people reinventing the new starter’s wheel. If they are the only ones available to train their replacements then the Method will deteriorate through that well-known party game of Chinese Whispers.

    Someone is going to have to provide an element of stability at the centre of the seconded group. This Subject Matter Expertise will provide the common core training to the Champions. It will assure the quality of their work to ensure that everyone is applying consistent best practice. It will support them with higher level skills and techniques to resolve the complex cases. It will collate and analyse lessons learned and look to improve the Method over time. The Champions will depend on them and so have a good incentive to see the right Experts are selected and supported by the organisation. The Experts get to work with the brightest and best (and most demanding). All in all, a much more positive outcome than the traditional Resident Expert will achieve.

    So, for the successful implementation of the Method, the best balance is to set up a core group / expert who can maintain and enhance it and to place a broader team of respected secondees around them to champion the Method across the organisation.

    Only the largest or most specialist organisations will have the manpower to staff such a centre of excellence fully. The credibility issue is so important that the Champions have to be local, known and respected. However, there is an argument for out-sourcing the subject matter expertise. Most of its skills will be reasonably generic and will be improved by wide experience. The Experts won’t need to know too much about organisation-specific work-flows and personalities. They will need to know the Method inside out and how to apply it appropriately within your organisation.

    An external Method hub will bring a breadth of experience and best practice. It also encourages an element of benchmarking competition between members and raises the bar for them all.

    Each organisation’s culture, context and budgets will determine where the centre of excellence will sit. It could be in-house, a shared service between similar organisations, a bought-in consultancy or a combination of the three.

    Business Method Centre of Excellence

    Finally, remember that nothing lasts forever. You’ve got your Method beyond being Flavour of the Month and into active use. It’s become ‘the way we do things here’. By all means, keep it going while it’s adding value but recognise when to stop. Don’t let it get in the way when something better comes along.

    Summary

    The core message boils down to:

    • You have to sell the concepts
    • Credibility is key
    • Senior sponsorship will not last unless tools are established in the processes that the seniors use.
    • Credibility in the workplace will depend on Champions. These should be respected peers or high-flyers seconded into the Method team
    • Champions will need Subject Matter Expertise to support them and to maintain and enhance the Method
    • The location of the Subject Matter Experts will depend on your organisation’s culture, context and budgets
    • Don’t keep pushing the Method when it’s stopped adding value
  • Goodwill

    In accounting terms Goodwill isn’t having nice thoughts towards other people. It’s what you pay for the intangible stuff. When you buy a business you don’t just pay the book value of the tools, stock and all the things you can see and touch. You also pay for the staff’s brains, the brand, the established customer base, the intangibles.

    Individually they’re unquantifiable, priceless. Mrs Jones is indispensable and everyone loves the company logo. Together, you know exactly what they are worth because you’ve just paid it.


    So why don’t we do this in our business cases? It would give us a consistent way to benchmark programmes and work to a common hurdle rate or value for money ratio. It might save a lot of grief and gaming around the enabling and infrastructure programmes where the direct identified benefits are less than the costs. It might also cull a few pet projects where saying we don’t need to count anything hides the fact that there is nothing to count.

    Usually, we garner the benefits for a typical public sector business case in the following order:

    • Cash-releasing, the hard savings that we can tick off against the costs
    • Non-cash, the efficiency and productivity gains described in money terms, not quite as good as real money though
    • Societal, the stuff outside our budget. “Do it online – save a bus fare!” again in money terms
    • Quality, just possibly the big strategic reason to do the project in the first place. Health and happiness, that sort of thing

    I dare say the private sector cases aren’t much different.

    All those quality benefits sitting in a table at the back of the business case. We can’t possibly price them but they must be big because they’ve a weighted score of 852/1000, whatever that means.

    We know what the programme has to deliver in RoI or VfM to meet the hurdle rate target it has been set. We have quantified the tangible benefits (cash, non-cash, public). So, the shortfall is the price of our intangible quality benefits. That’s the goodwill, the overall value we put on all the hard to measure stuff to justify our investment.

    Once the quality benefits have been costed like this, we have a way to benchmark our programmes. We can set a common hurdle rate. We don’t need different rules where the mundane stuff must make a profit but the innovation doesn’t have to break even. Instead, we can see how crucial the quality benefits are to each programme. How big is the goodwill relative to the quantified benefits and the costs? Is it a figure we can live with? Are we comfortable that our quality benefits will be sufficient to justify it?

    So, what gets in the way? Goodwill is the programme’s willingness to pay. To find it, you get the relevant people together and ask, “How much would you pay for X?” It’s open to anchoring, group-think and a host of other errors and abuses but it’s not alone in this. The programme cost estimates will be going through exactly the same set of biases. In this case we’re not asking, “How much would you pay?” but, “Would you pay this much?”. A much more closed and leading question.

    The accuracy and consistency of the price will vary widely over time and between situations and individual opinions. The market we work in isn’t perfect. The analogy here is more the Stock Market than the Supermarket. With stocks and shares things are much more fluid and the prices are nowhere near as stable. So long as we treat our intangibles more like shares than cereal there’s no reason why we can’t put a price to them though.

    I suspect that what will really get in the way is its transparency. It opens up judgement calls to scrutiny, which is not the greatest motivator.

    Does anybody want to give it a try?

  • Haggling Over The Price

    “We’ve agreed what sort of benefit it is, now we are simply haggling over the price.”

    If you look hard enough, there are no qualitative benefits. How should we measure the benefits we create for our customers / service users? If the new system will improve lives, how much of an improvement will it be? Where’s the breakeven point that shows if we’ve spent wisely?


    Instead, I see business cases that say this stuff is qualitative and shouldn’t be given a money value. If it’s to be measured at all then it will be in a table of weighted scores buried in an appendix where no-one will give it much thought. There we can compare quality benefit A against quality benefit B. What we can’t do there is compare quality benefit A with cost £C.

    So how can we ever tell if the investment is worthwhile? When we make comparisons between our quality benefits we create a currency for them. A is worth more quality points than B so within our business case we have a local currency of ‘Quality Points’.

    That currency can be converted to any other and at some point we can match our Quality Points for £s. I know that it’s not real money. We won’t end up with a bag of cash. What we will get is a sense of scale, a feeling for just how relatively important these benefits are. We have a means to compare our local project against all the others.

    The exchange rate depends on the market involved. I accept that the market is going to be small and imperfect. It’s going to be the stakeholders in the portfolios around our project. It will be their willingness to pay for all the various options they face that will determine the relative value of our benefits.

    When our projects take this approach, the portfolio doesn’t have to choose between your weighted score and mine without knowing how we picked our weights. Their choice won’t be perfect but it will be a bit more rational and fair.

    “Would you pay £50 for this benefit?”

    “Certainly”

    “Would you pay £50,000?”

    “Of course not”

    “Then we’ve agreed what sort of benefit it is, now we are simply haggling over the price.”

  • Management Cluedo

    Means, Motive and Opportunity

    Means, motive and opportunity, it works for murderers so why not for managers?
    • Motive, the force (external or internal) that gives you the need to take action
    • Means, the relevant physical and intangible resources you have that enable you to take action
    • Opportunity, the suitable time and place where you can take action


    The Modus Operandi

    No good detective thriller is complete without a decent modus operandi, the killer’s cunning combination of means, motive and opportunity.
    The motive sparks their desire. It may be as simple and obvious as the need for money. It can be subtle, personal and indeed perverse (given that murder is in itself wrong, we might be looking at degrees of perversity here).
    The means, as cheap and brutal as Cluedo’s trusty old lead pipe or as convoluted as an Agatha Christie plot.
    The opportunity may be a one-off set of circumstances where the killer must decide and strike on an impulse. Or it may be a regular occurrence that gives them time to plan and practice for the perfect crime. Is Professor Plum a casual visitor to the library or can you set your watch by him?

    So that’s the story for murderers, where do the managers come into this?
    The motive also sparks managers’ desire. Where managers differ from murderers is that their motive may not come naturally. If you don’t have a spark of inspiration then go looking for ideas. It’s important to have a motive though. You can’t afford to sit back and let events wash over you. If you do then you will become the victim of other people’s motives.
    Creativity doesn’t have to be a flash of inspiration, it can come from a thorough analysis of what’s gone before and what the future looks like with all the things you have at your disposal. The means shows you what’s feasible, and it may be more than you first thought. Consider the resources you have or can obtain. It’s not just a question of assets, it’s a matter of capability as well. Back in criminal terms, get the best accomplices you can.
    The opportunity, strike while you can. Recognise that there will be a limited window of opportunity of time and place when things are just right. Act too soon and you’ll blow it. Wait too long and you will miss your chance. As a rule of thumb, act sooner, rather than later. Even if it all fails, you will be happier knowing that you tried.

  • Money in Weighting

    How do you choose between options when you can’t put a price on them? When you are comparing the multiple criteria in your decisions, what currency do you use? How can you make it ‘common currency’?

    You’re building a case to invest and you use points to prioritise the results we want to see and the extent to which each option will deliver them.


    It’s a good way to add some rationality to the business case but it might not paint the whole picture of how important your project is in relation to everything else you have to do.

    Money is tokens of relative value. It is the middle-man in a barter system. I swap the stuff I do / make for money that I then swap for stuff you do / make. So, if money is just tokens then it’s basically no different from gold stars, Brownie Points or whatever currency we use for quantifying the intangible things we seek.

    In my imaginary Bureau de Change I can convert any currency to another once I know the market rate. Sadly, we work in imperfect markets that make it difficult to convert between these currencies. I can ask what you would be willing to pay but willingness to pay is subjective. It is limited by the players involved, the context in which they operate, even the time and place where they make their decisions. It’s too hard and costly to do so people don’t use it in their options appraisals.

    However, willingness to pay in £s really isn’t much different from assigning point values to options. The points will also depend on people and circumstances. We just feel more at ease with points because they are not real money.

    Maybe it’s because we’re not playing with real money and can’t be held to account for the points we ‘spend’ that we inflate the importance of the quality options. When we pick up to 100 points on our options, we are only ranking them against each other. Nowhere does it say that the best option is only worth 50 points in the whole scheme of things.

    An alternative is to use money. Instead of 100 notional points, allocate the actual discretionary spend budget. How much free money do you have to splash out on something new? If you have £50k to spend then decide how much out of the £50k each option is worth.

    You are now starting with a sense of proportion. It’s now real money, not imaginary tokens. If you’ve got £millions to play with then it’s serious. If you’ve only got a couple of hundred then stop sweating blood over trivia.

    Once you are comfortable with the sense of proportion then there’s another piece of reality to bring into the mix. That’s the matter of comparing what you can spend on this project against what you are spending on everything else that you could do. Determine your total discretionary spend. Think about all the new stuff you want to do as well as this particular project. If you’ve got a formal costed list, all well and good. If not, just go with your gut feel.

    Take your total discretionary spend figure and split it between this project and everything else. Say you have £1M and this project isn’t so big or important, so you split it £50k for this and £950k for everything else. Write at the top of all your options appraisal workings (put it in the document header if you must): “This project £50k, everything else £950k”

    Use this as a reminder of your project’s relative worth before you even start appraising the options within it.

    When you’ve done all this and quantified your options in terms of £s, remember that it isn’t real money and it can’t be put against your costs. At the end of the day, it’s all still a comparison of relative value using tokens. This time though, the tokens are more realistic and the final decision made with closer acquaintance to real life.

    If you want to do that then you have to do the full SRoI, focus group, willingness to pay exercise to make a fair comparison between costs and benefits.

  • Mature Decisions

    Everybody likes a Maturity Model these days. It’s the management version of Top Trumps. So before you worry about how mature your enterprise is at doing stuff, here’s where you consider the stuff you choose to do in the first place. How good is the process around the business choices you make? Would you like to make it better or are you happy that your luck will continue to see you through?


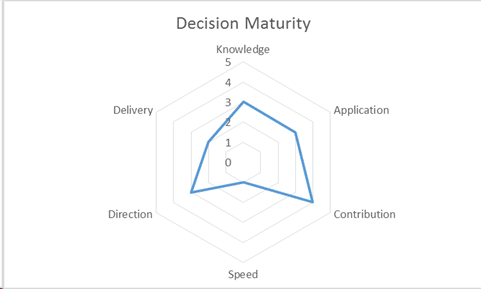
    With a score of 5 being perfection and 1 being, “I’m sorry, were you talking to me?” what would you score against these topics?:

    • Depth and breadth of knowledge behind the decision
    • Application of knowledge to the decision
    • Stakeholder contribution to the decision process
    • Decision cycle speed
    • Giving direction
    • Confidence in delivery

    Where do you sit on the maturity scale when it comes to making business decisions?

    A spider diagram of decision maturity scores

    Where would you be on this chart? Does it give you pause for thought?

    Waller’s Decision Maturity Model

    Fives. Omniscience, omnipotence, alacrity and economy

    Knowledge – You know all the relevant information that will inform your decision.

    Application – You weigh it and apply it appropriately in making your best choices.

    Contribution – All the relevant stakeholders contribute to the decision to the best of their ability.

    Speed – Your decision cycle is minimised. Results are achieved as quickly as is possible.

    Direction – You convert the decision to clear, concise direction that motivates your stakeholders to act towards a common goal.

    Delivery – Stakeholders act on that direction to deliver your desired outcome in the most efficient manner.

    Fours. On the upper slopes

    You just about know it all. You meet very few surprises.

    You use rigorous methods to apply what you know when making choices and you understand what the consequences will be.

    You actively consult widely. Most stakeholders contribute to the decision to the best of their ability.

    Your decision cycle is optimised with no un-necessary delay. You do not sit on decisions.

    You give clear direction so people know what they must do.

    Stakeholders act on your direction to deliver a satisfactory result within the tolerances you have set.

    Threes. Middle ground

    You are reasonably comfortable with what you know. You understand the situation better than most around you.

    You apply what you know to your decision but recognise that you still have areas of uncertainty.

    You have active contribution by some Stakeholders. The ‘usual suspects’ chip in with their ideas.

    You have a recognised decision cycle and allow decisions to be reviewed iteratively, e.g. Plan, Do, Study, Act.

    You put what you want into words that most of your people understand.

    People mostly do what they should but you expect to make a few mid-course corrections when they stray from your path.

    Twos. Mildly embarrassed by your performance

    You know that you don’t know it all

    There’s a nod towards strategy in your template Business Case.

    You know you have some Stakeholders and you talk to your favourites.

    You’ve missed the boat a few times and you know you’ve got to be quicker next time.

    You think you’ve said what you want doing.

    Stuff happens but people keep coming back with difficult questions about what they think they should be doing.

    Ones. What problem?

    “I didn’t get where I am by sitting around researching stuff.”

    “Something must be done. This is something. Let’s do it. Why waste time on a Business Case?”

    “I know what people want.”

    “This creative stuff is an art, you can’t rush it.”

    “You all know what to do. Carry on.”

    “Does anyone here know what we’re meant to be doing?”